- Start Your BusinessStart Your Business
- Starting a BusinessThe tools and resources you need to get your new business idea off the ground.
- PaymentsEverything you need to start accepting payments for your business.
- Funding & CapitalResources to help you fund your small business.
- Small Business StoriesCelebrating the stories and successes of real small business owners.
- Self-EmployedThe tools and resources you need to run your own business with confidence.
- Run Your BusinessRun Your Business
- Running a BusinessThe tools and resources you need to run your business successfully.
- AccountingAccounting and bookkeeping basics you need to run and grow your business.
- Cash FlowTax and bookkeeping basics you need to run and grow your business.
- PayrollPayroll essentials you need to run your business.
- TaxesTax basics you need to stay compliant and run your business.
- EmployeesEverything you need to know about managing and retaining employees.
- Grow Your BusinessGrow Your Business
- Growing a BusinessThe tools and resources you need to take your business to the next level.
- Sales & MarketingSpread the word: What you need to know about marketing your small business.
- FundingHow to find funding and capital for your new or growing business.
- Midsize BusinessesThe tools and resources you need to manage your mid-sized business.
- Enterprise Suite BlogThe tools and resources you need to grow your own business with confidence.
- E-CommerceHow to start and run a successful e-commerce business.
- TaxesTaxes
- How to fill out a 1099-NEC formLearn how to fill out and file 1099-NEC forms for independent contractors and freelancers.
- How to file small business taxesLearn how to navigate tax season with confidence and minimize your tax liability with this guide.
- Small business 1099: What you need to know for 2025Navigate the complexities of small business 1099 forms and filings with our comprehensive guide.
- 13 documents to give your accountant for small business taxesYour accountant will need these documents to file your small business taxes successfully.
- What's NewWhat's New
- NewsBrowse the latest news, press releases, and reports from QuickBooks.
- AI Resource HubFind the latest on Artificial Intelligence.
- Small Business DataThe latest research and insights for Small Businesses from QuickBooks.
- Small Business StoriesCelebrating the stories and successes of real small business owners.
- Holiday SuccessEverything you need to thrive during your business's busiest seasons.
- AI InnovationsBrowse the latest AI innovations in QuickBooks on the Intuit platform.
- ToolsTools
- All ToolsFree accounting tools and templates to speed up and simplify your workflow.
- AI-Powered Invoice GeneratorTry out this free invoice generator to create an invoice online using Intuit Intelligence.
- Payment Cost CalculatorFind out how much you could save by switching to QuickBooks Payments.
- Paycheck CalculatorAccurately estimate pay for all your employees.


Startup costs: How to budget and maximize tax deductions
Table of contents
Table of contents
Key tax updates for filing taxes in 2026:
- Section 174 R&D capitalization rules: The One Big Beautiful Bill Act has permanently reinstated the option for businesses to deduct domestic R&D costs in the year they're fully incurred for tax years beginning after December 31, 2024. This reverses the mandatory five-year amortization requirement and restores a more favorable approach for companies that invest in innovation.
- Section 179 and bonus depreciation: The OBBBA also permanently restores 100% bonus depreciation for qualifying property acquired and placed in service after January 19, 2025. Additionally, the Section 179 deduction limit was significantly increased to $2.5 million, with a phase-out threshold of $4 million for assets placed in service after December 31, 2024.
- 1099-K reporting thresholds: The OBBBA has repealed the lower 1099-K reporting thresholds, reverting the requirement to the original standard of over $20,000 in gross payments AND more than 200 transactions.
- Other deductions to consider: The rules for business startup costs remain unchanged, allowing a deduction of up to $5,000 in the first year, with a phase-out for costs over $50,000. Remaining costs can be amortized over 15 years, so keeping detailed records remains crucial for both deductions and audits.
Few things are as exciting as starting a new business from scratch. But you must first determine which startup costs are required to get your business off the ground. Without proper due diligence and calculation, your company might be going out of business before it can succeed.
Tracking expenses, understanding your business startup cost budget, and leveraging potential tax deductions can all help optimize your financial position, allowing your business to thrive.
Read on to learn the basics of accounting for startup costs, what to consider when calculating them, and what you might be able to deduct from your taxes.
Understanding business startup costs
Understanding the functions of different business startup costs is key to future success. Startup costs can be one-time or ongoing, meaning they are paid throughout the business's lifespan.
Business registration costs are considered one-time, as you only need to pay a one-time fee to register. However, ongoing legal fees need to be paid throughout the business's life.
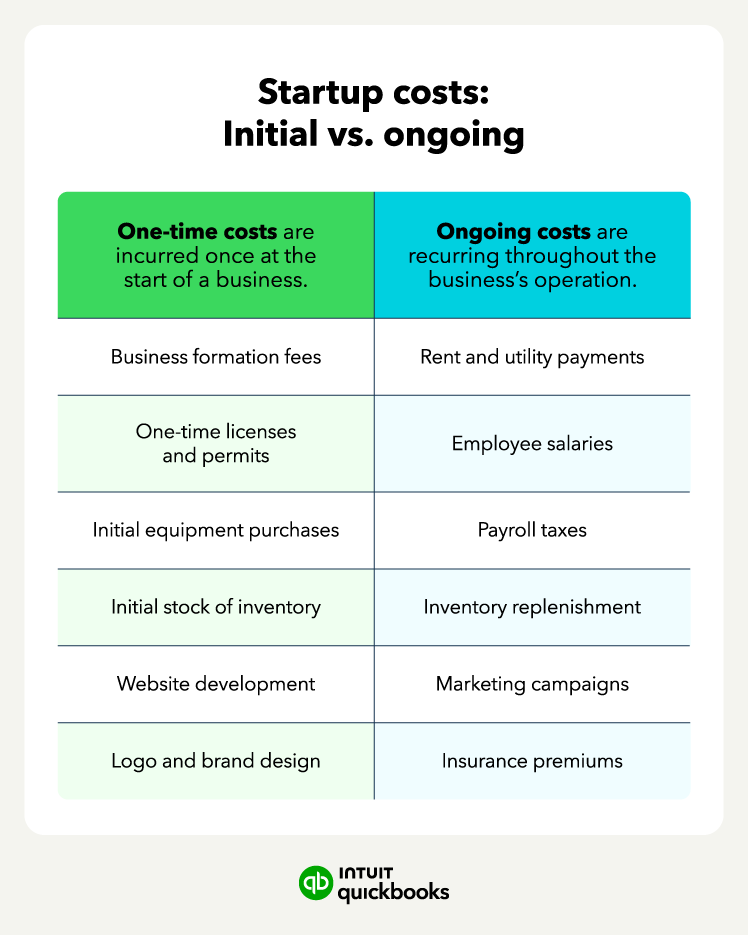
You’ll also need to spend money on equipment and technology to run your business. Initial equipment and furniture costs are one-time (just think—you don’t buy a new printer daily).
However, equipment repair or replacement costs are considered ongoing, even if you don’t spend that line item every month. When considering the startup costs of inventory, you have two different costs: the initial inventory (one-time cost) and the replenishment inventory (ongoing).
It’s important to note that different businesses, industries, and business models have different startup costs. For example, starting an online business generally costs less money than starting a brick-and-mortar business simply because an online business requires less physical space.

For tax purposes, it’s important to keep records and receipts for both kinds of expenses throughout the process, at least for three years from the year of spending.
The tax implications of startup costs
In the year that the business begins operations, business owners can deduct up to $5,000 of startup costs. However, if your total startup costs go over $50,000, this deduction is phased out dollar-for-dollar, and any remaining costs over the initial $5,000 deduction can be amortized over the next 15 years, allowing you to claim more.
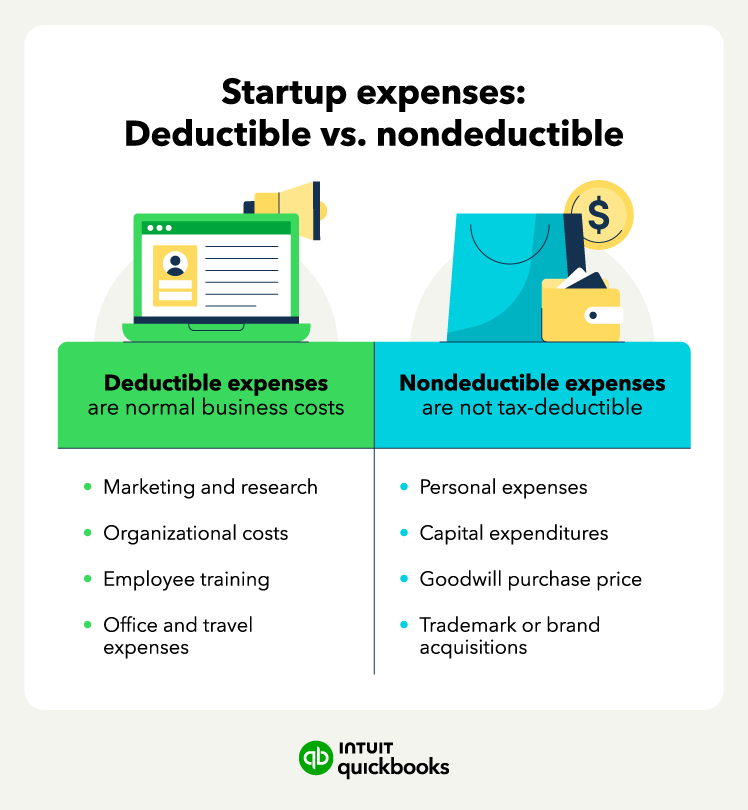
The most important concept to know is: what is considered deductible versus nondeductible.
Startup cost deductions are those that you can generally deduct for an established business, and the same goes for nondeductible startup expenses. If you cannot typically deduct it, you cannot deduct it now.
Consult with a tax professional when working through the tax implications of startup costs. Since tax laws are always subject to change, working with a CPA or QuickBooks Accounting professional can save you a lot of hassle when it comes to tax time.
Feel confident from day one
You're never too small, and it's never too soon to know you're on track for success.
How to calculate your startup costs
Sometimes, you can start a business with no money, but most often, you’ll need some funds to get started—the question now is, how much? As nice as a crystal ball would be to tell you precisely what you need, there are ways to calculate a decent ballpark figure to make sure you’ve covered all your bases.
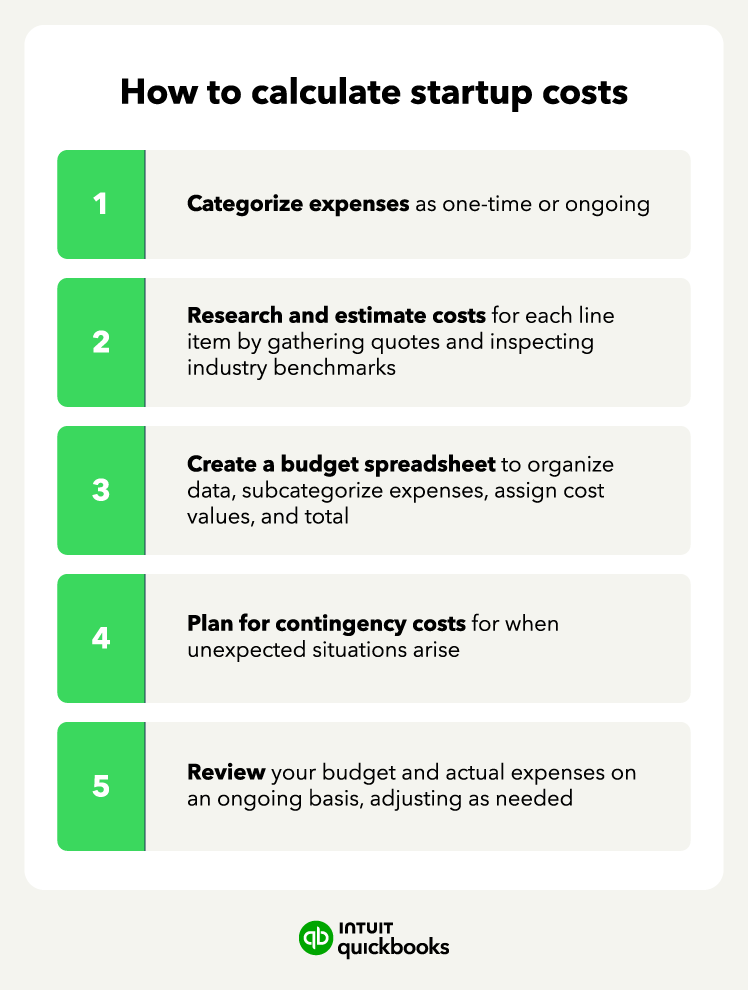
When estimating business startup costs, it’s critical not to underestimate overhead, including utilities, maintenance, and insurance.
Another common cost estimation mistake you can avoid is not preparing for inflation. While you might not know exactly how much costs will rise, factor in increases in rent and the cost of goods over time.
To help you research and estimate appropriate startup costs, you can consult the Small Business Administration for helpful resources and tools. QuickBooks has the resources, tools, and features to customize estimates and project profitability, making starting your own business hassle-free.

A good rule of thumb is to dedicate between 10% and 20% of your total startup costs toward an emergency fund. You’ll never know when you might have equipment failure or unexpected delays.
Funding to cover startup costs
Depending on the total startup costs required, you might need business funding. While you can certainly use your personal funds to cover startup costs and have no loans to repay, that can deplete your savings quickly or put you into personal debt for your business—not a suggested move.
Small business loans
A small business loan can provide access to larger amounts of money than a personal savings might. However, to qualify, you must meet lender requirements, like having a solid business plan or a specific credit score.
Investor funding
You can also participate in investor funding through angel investors, crowdfunding options, and venture capitalists, each with pros and cons. Investor funding allows you even more access to higher amounts of capital plus industry connections, but you do lose part of ownership equity to them.
Small business grants
Some small business grants are available to startups that provide money that does not need to be repaid. While these are a great way to fully or partially fund startup costs, they are highly competitive, and most have very specific eligibility requirements.
Startup costs by business structure
The type of business structure you choose will impact your startup costs. Sole proprietorships are often associated with the lowest costs since they are relatively straightforward. LLCs, however, can have moderately higher costs due to their complex nature and legal requirements.
It’s important to note that the business structure isn’t the only factor in how high (or low) your startup costs will be—other factors like industry, location, and overall business complexity all play an important role.
Money-saving strategies for startups
While it’s impossible to avoid all startup costs for a business, there are strategies to help minimize them so you spend less to get your business off the ground:
- Minimize space needed when possible by working from a home office to reduce the need for property, or outsource some work to virtual assistants to minimize physical bodies.
- Leverage technology, such as ERP solutions, to minimize the number of employees needed (bonus points if you use a cloud-based ERP to reduce the space required).
- Learn the art of negotiation to potentially get better deals with suppliers or rent reductions.
- Keep control of inventory managementto ensure you don’t have an overstock of inventory that isn’t being sold.
- Learn financial discipline to ensure that the startup budget you created is being followed as closely as possible and that money is being saved if it can be.
Key considerations for startup costs
Before launching a business, it’s important to understand the factors that influence startup costs and how to manage them effectively. From industry-specific needs to seasonal shifts, every decision you make in the early stages can have lasting financial implications. The following points highlight essential things to keep in mind as you plan your budget.
Startup costs differ across industries
Several factors impact startup costs across different industries. Manufacturing, construction, and energy industries tend to have higher startup costs because they require special equipment and infrastructure. However, industries like e-commerce and service-based businesses tend to have lower startup costs because they don’t need as much physical property.
Seasonal fluctuations affect initial startup costs
Inventory, labor, marketing, and equipment costs can all be affected by seasonal fluctuations. Depending on the season, these costs can be dramatically higher or lower, so it’s important to consider seasonality regarding your business when determining startup costs.
Creative ways to reduce startup costs
Minimize overhead by working out of a home office, bartering goods or services with other businesses, and using social media for low-cost marketing. Other entrepreneurs have performed crowdfunding to raise capital, and some have offered pre-orders to help generate revenue ahead of truly opening.
A portion of startup costs should be set aside for emergencies
While there’s no perfect amount, a general rule of thumb is to set aside 20% of your startup costs for emergencies, like equipment repair, natural disasters, or economic downturn.
Sharing startup costs with a business partner has pros and cons
While sharing startup costs can significantly reduce one’s financial burden, differing business decisions could ultimately lead to turmoil within the business.
Documentation is essential for legal and financial protection
Keeping accurate documentation is essential for proper financial reporting and legal protection against audits or disputes. You should keep the following documentation up-to-date:
- Comprehensive business plan
- Startup cost budget
- Bank statements
- Loan agreements
- All related receipts and invoices
- Relevant legal documentation
- Vendor and supplier contracts
- Business financial statements
Start your business with confidence
Looking over startup costs' ins and outs, you might feel a little intimidated. Yes, a lot that goes into a startup, but think of it as an investment. Startups bring with them an unprecedented amount of freedom.
Start tracking what you need for your startup, keep documents and receipts from all purchases, and stay organized with QuickBooks Online. Make sure you’re aware of all appropriate forms—contact your tax specialist or accountant when in doubt—and you’ll have a startup to call your own in no time.
You could save up to 25% on transaction costs².
Speak with us now to see if you qualify.
Talk to sales 1-800-515-8366
Monday - Friday, 6 AM to 4 PM PT
Payroll Compliance
Details on the One Big Beautiful Bill Act and how it affects payroll
USPS changes may affect your postmark date
Mandatory State Paid Family Leave Programs
Accounting

Here’s what’s new in QuickBooks Online for August 2026

The accounting equation: A beginner’s guide with examples
Customer Stories

Why Amborella Organics trusts QuickBooks AI to handle the heavy lifting of a $10M+ vision
At Petal Salon, Amanda Lee Harvey keeps her clients in the pink

Normal Ice Cream saves 7 hours a week on banking admin thanks to QuickBooks Bill Pay
How The Baby Pantry shows up for families in need
Recommended for you


Explore what you can do with QuickBooks
Explore what you can do with QuickBooks

See profit at a glance


Get expert help
Looking for something else?
Firm of the Future
Topical articles and news from top pros and Intuit product experts.
QuickBooks Support
Get help with QuickBooks. Find articles, video tutorials, and more.
Call Sales: 1-800-285-4854


© 2026 Intuit Inc. All rights reserved.
Intuit, QuickBooks, QB, TurboTax, Credit Karma, and Mailchimp are registered trademarks of Intuit Inc.
Money movement services are provided by Intuit Payments Inc., licensed as a Money Transmitter by the New York State Department of Financial Services. For details about our money transmission licenses, or for Texas customers with complaints about our service, please click here.
By accessing and using this page you agree to the Website Terms of Service.