
You could save up to 25% on transaction costs².
Speak with us now to see if you qualify.
Talk to sales 1-800-515-8366
Monday - Friday, 6 AM to 4 PM PT

Table of contents
Table of contents
What every taxpayer should know about itemized deductions:
If you’re dreading your tax bill this season, the small business deductions you choose to claim can make all the difference in how much you’ll owe (or save). And according to a QuickBooks entrepreneurship report, more than three in ten business owners have made tax filing errors, possibly missing out on valuable deductions.
As we head into tax season 2026, all taxpayers are deciding whether to take the standard deduction or itemize personal or “individual” expenses to reduce their taxable income. When you’re self-employed or a small business owner, the line between personal and business expenses can sometimes get blurry. Depending on your situation, itemizing your deductions may offer you additional tax savings.
Let’s dive into everything you need to know about itemized deductions for the 2026 tax year, including the most common ones and the forms you’ll need to file.
Itemized deductions are specific personal expenses that the IRS allows you to subtract from your income to reduce how much of it is subject to tax. Instead of taking a single flat deduction, you claim eligible expenses individually.
The amount you can deduct depends on what you actually paid during the tax year and whether the expense meets IRS requirements. For example, someone with $90,000 in adjusted gross income (AGI) and $22,000 in eligible itemized deductions would have $68,000 of taxable income ($90,000 minus $22,000).
To claim your itemized deductions, you’ll use Schedule A (Form 1040) to list and calculate your eligible expenses. You’ll then subtract the total from your gross income. What remains is your taxable income.
Here is an example of how a Schedule A might look:
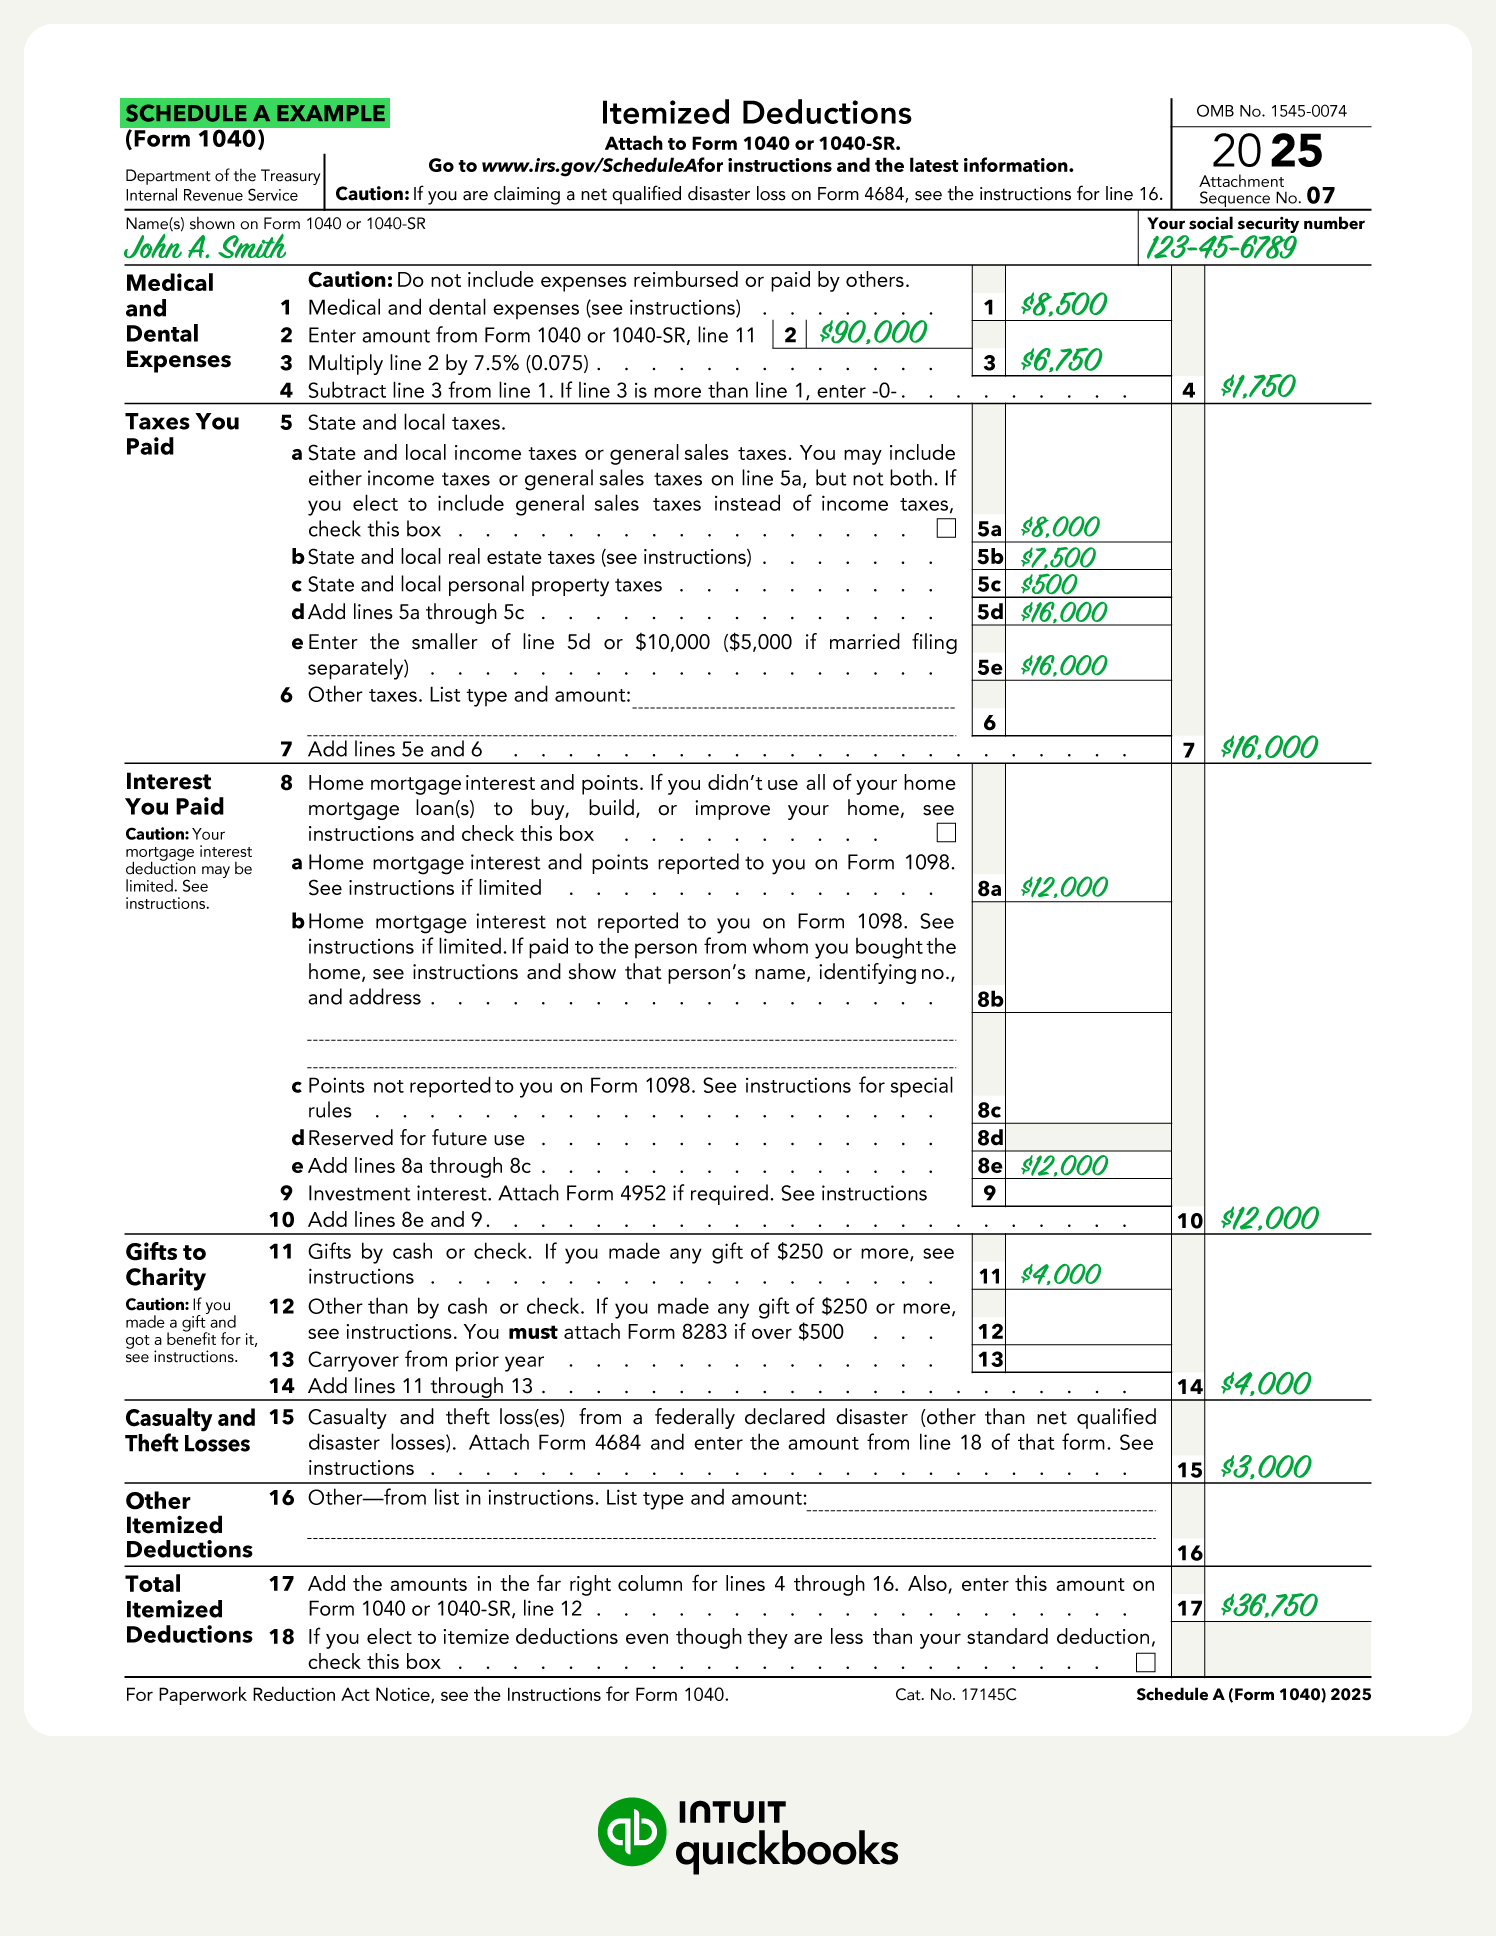
You can find detailed instructions for the eligible expenses on the IRS website. Make sure you keep receipts for all of your business-related expenses.
After adding up your eligible expenses, you can compare them to the standard deduction. You’ll only want to itemize deductions if the total amount is greater than the standard deduction. While it generally takes more time and effort to keep up with receipts throughout the year, it’s worth the bigger tax refund or smaller tax bill.

Itemize deductions only if they exceed the standard deduction—though it takes more effort, the payoff could mean a bigger refund or smaller tax bill.
An itemized deduction lets you claim specific individual expenses, while the standard deduction lowers your taxable income by a preset amount. These set amounts are based on your filing status and are adjusted annually by the IRS.
The standard deduction amounts for the 2026 tax year are:
If you are 65 or older or legally blind, you’re eligible for a higher standard deduction.
For 2026, single or head of household filers can add $2,050 per condition, while married taxpayers (filing jointly or separately) can add $1,650 per condition, per person. For instance, if you’re a single filer who is both 65+ and blind, your total standard deduction would increase to $20,200.
Taxpayers ages 65 and older can now claim an extra $6,000 deduction, on top of the existing age 65+ standard deduction described above. Married couples can claim $12,000 if both spouses qualify.
This tax deduction is available whether you itemize or take the standard deduction, and it applies to tax years 2025 through 2028. It phases out for taxpayers with modified adjusted gross income over $75,000 (single) or $150,000 (married filing jointly), and is fully phased out at $175,000 (single) or $250,000 (married filing jointly).
If you're a nonresident alien, or if you're married and filing separately and your spouse itemizes, you’ll itemize your deductions. You can't take the standard deduction.
Itemized deductions include a range of expenses from both personal and self-employed business transactions. Below are the most common expenses you can write off:
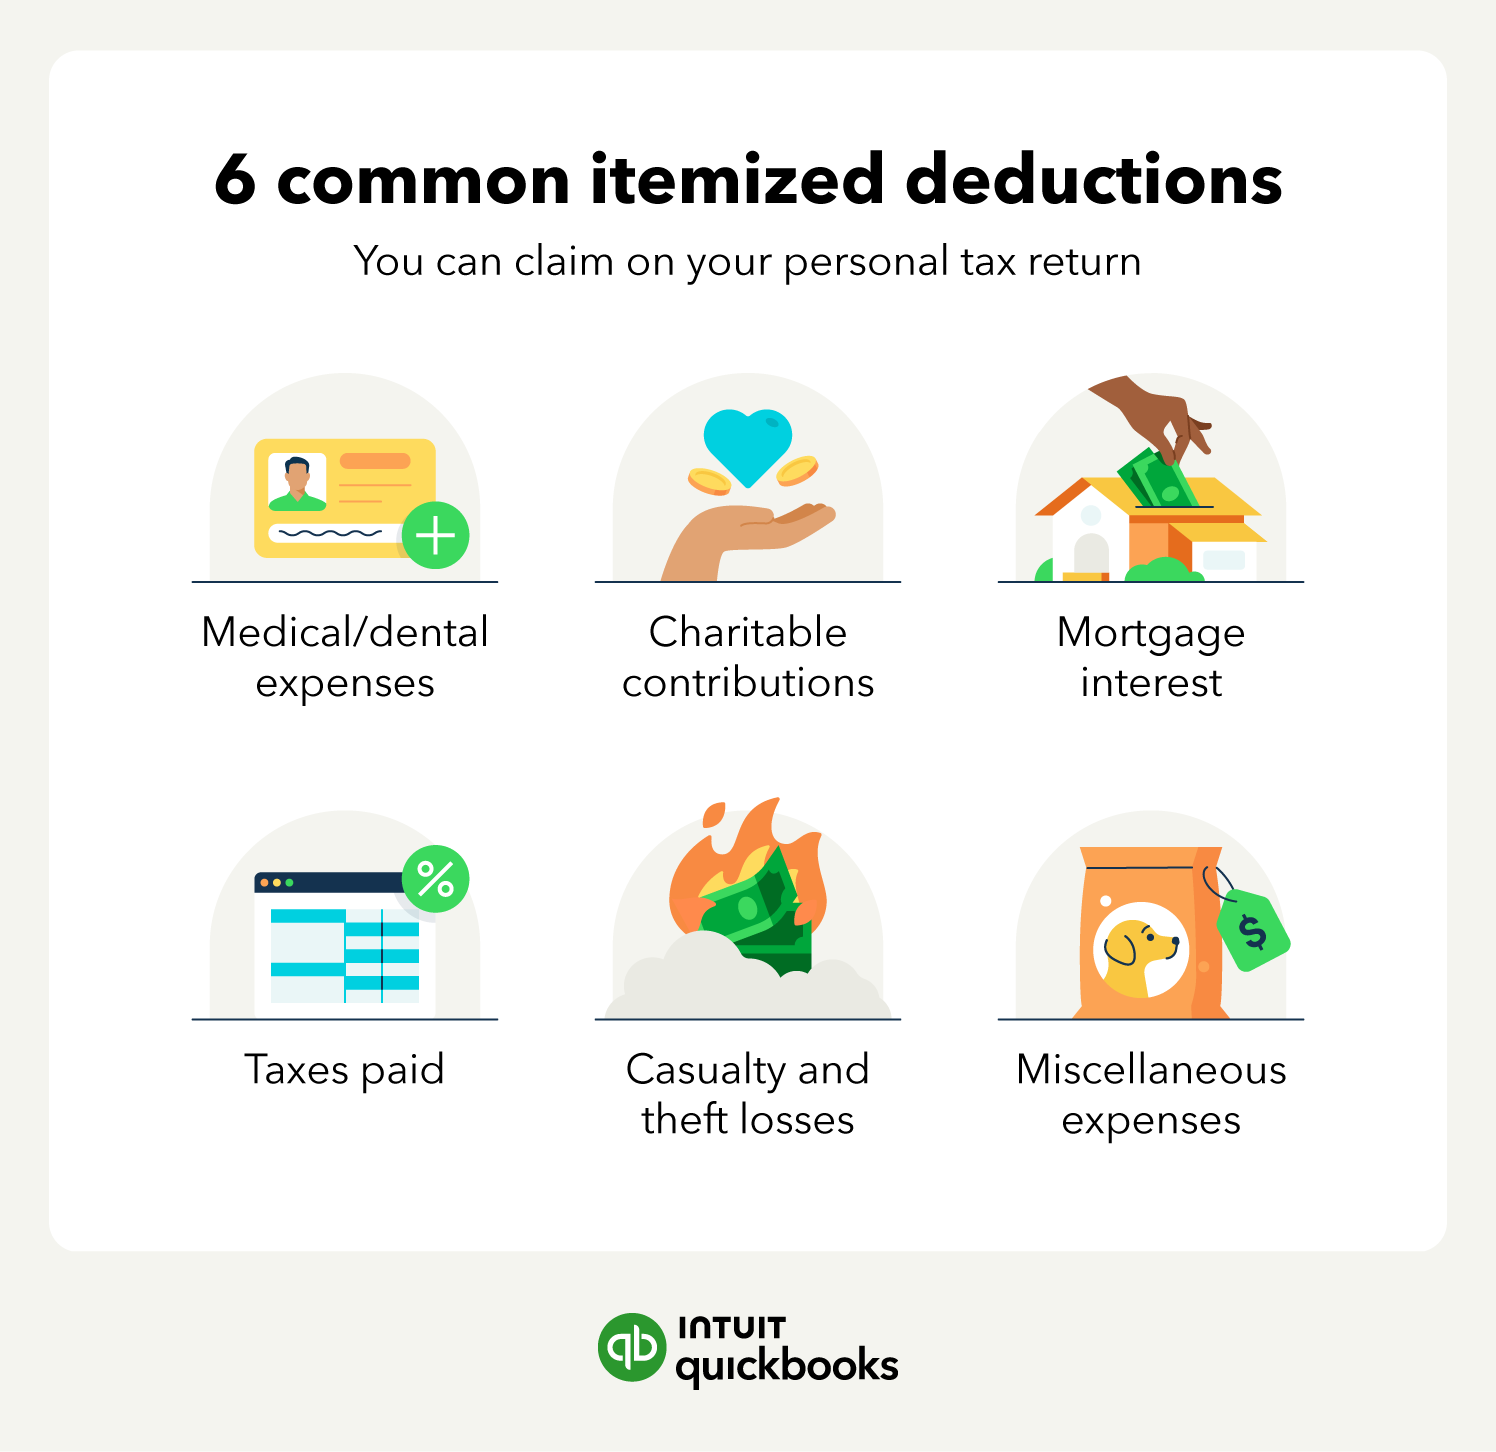
Medical and dental expenses can represent a significant portion of your annual budget, especially if you’ve had major health-related costs.
These expenses offer taxpayers a valuable opportunity to reduce taxable income through deductions, making them a critical consideration during tax season.
Some common examples of deductible medical and dental expenses:
But remember, not all expenses are eligible for deduction. To claim these costs as itemized deductions, the total must exceed 7.5% of your Adjusted Gross Income (AGI).
Additionally, you cannot deduct any costs reimbursed by insurance, employer-sponsored plans, or other sources. Over-the-counter medications, cosmetic procedures, and general wellness expenses (like gym memberships) are also excluded.
Use employee health benefits like a health savings account (HSA) or flexible spending account (FSA) to cover medical expenses with pre-tax dollars, reducing your overall taxable income even further.
You can deduct state and local taxes (SALT) to help reduce your taxable income. These deductions can include real estate, state, and local income or sales taxes you paid during the past year. If you occasionally rent out your home or a portion of it, you can still claim these deductions, provided the rental period does not exceed 14 days per year.
Here are the types of taxes you can deduct:
Keep in mind that these deductions are capped at $40,400 for most taxpayers for 2026 ($20,200 if married filing separately). The cap rises by 1% each year through 2029, then reverts to $10,000 starting in 2030.
However, if your modified adjusted gross income (MAGI) is greater than $505,000 for 2026 ($252,500 if married filing separately), the amount you can deduct is reduced by 30 cents for every dollar you earn above that threshold. This "phase-out" continues until the cap hits a minimum floor of $10,000.
Additionally, if you itemized these deductions in the previous year and received a tax refund, that refund must be reported as income on your current-year tax return.
Compare your state and local income taxes paid to the IRS sales tax tables to see which deduction is higher. With the SALT cap now at $40,400, choosing the larger deduction can have a much bigger impact on taxable income than in years past.
If you own or pay the mortgage on your home, you can and should receive a deduction on your mortgage interest. Your mortgage lender should send you a Form 1098 outlining the deductible interest and points, which are charges associated with getting a home mortgage, that you’ve paid over the past year.
You may also be able to deduct certain mortgage points that you’ve paid if you’ve:
Keep in mind the mortgage interest limits: The deduction is only for the first $750,000 of mortgage debt for your first or second home (or $375,000 for married couples filing separately).
However, if your home was purchased on or before December 16, 2017, that limit is higher, allowing you to deduct interest on up to $1 million of debt ($500,000 each for married couples filing separately).
If you refinanced or purchased a home in the past year, check if you paid mortgage points. These could be deductible in addition to your interest.
Charitable contributions are a meaningful way to give back to your community and a valuable opportunity to reduce your taxable income.
Whether you donate as an individual or through your business, these gifts to qualified organizations can be claimed as itemized deductions, often leading to significant tax savings.
Some common examples of deductible charitable contributions:
If you’re filing as an S corporation or a partnership, your portion of the business’s charitable contributions will be reported on the Schedule K-1 issued to you by the business. You’ll then report your share of these contributions on Schedule A of your personal tax return.
For individual taxpayers, cash contributions are generally limited to 60% of your Adjusted Gross Income (AGI), while noncash contributions may have lower limits.
Starting in 2026, a new rule requires you to clear a floor before your charitable giving counts toward your itemized deduction. Only the portion of your contributions above 0.5% of your adjusted gross income is deductible. For example, if your AGI is $100,000, the first $500 you give doesn't count toward your itemized deduction.
Also new for 2026: Even if you don't itemize, you can now deduct up to $1,000 in cash charitable contributions ($2,000 if married filing jointly) directly. This is separate from the itemized deduction covered in this section, so it's worth a look if you're leaning toward the standard deduction.
Donating appreciated stocks or assets directly to a charity lets you avoid capital gains taxes while claiming the full market value as a deduction.
Casualty and theft losses can be claimed as itemized deductions on your tax return only if the loss is attributable to a federally- and state-declared disaster. These deductions are limited to unreimbursed losses, meaning you’ll subtract any insurance payouts you received or expect to receive.
Eligible disaster-related losses may include:
Note that these are personal casualty losses claimed on Schedule A. Casualty losses to business property are typically handled on Schedule C or through your business's tax return instead.
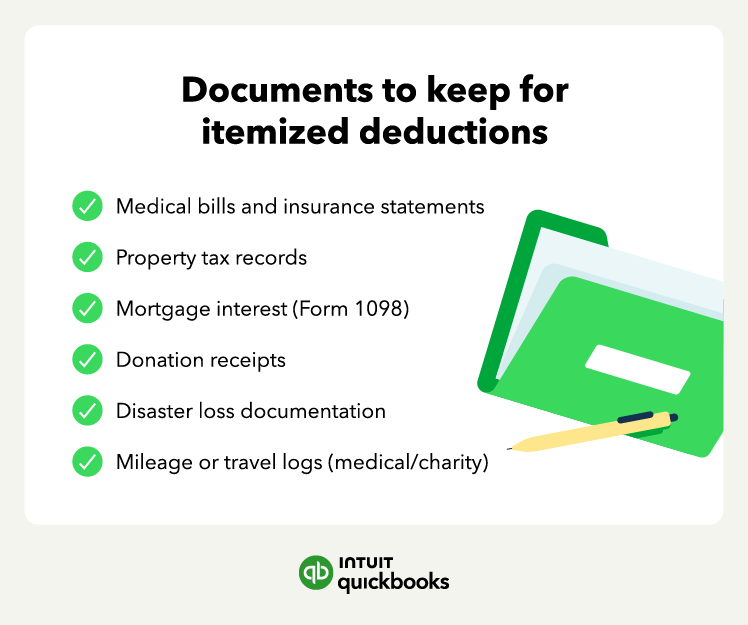
You can deduct your casualty and theft losses on Schedule A, but keep thorough records of the damage, including receipts, appraisals, and photos. Consider working with a tax professional to maximize your claim and navigate the rules for more complex situations, especially if you’re affected by a federally declared disaster.
If you’ve been impacted by a disaster or theft, check if your area is included in a federal disaster declaration. It can significantly broaden the scope of losses that qualify for a tax deduction.
There are also less common, miscellaneous personal expenses you can itemize, including gambling losses and federal estate tax on income.
Starting in 2026, gambling losses are subject to a new limit. You can only deduct 90% of your losses, and only up to the amount of your gambling winnings for the year. Previously, gamblers could deduct 100% of their losses (still capped at winnings). Keep this in mind if you regularly report gambling income or losses.

Depending on your unique situation, one type of deduction may work more in your favor than the other.
Pros of itemized deductions:
Cons of itemized deductions:
Although it’s a time-consuming process, the extra steps required for itemized claims may be worth it for the amount of money you’ll save in taxes.

Since you can’t claim both standard and itemized deductions, figure out your adjusted gross income first to determine which one gives you the greatest deduction. If your itemized deductions exceed your standard deduction amount, you will claim all of your expenses on Schedule A (Form 1040) with your tax return.
Here’s how:
1. List your deductions on their corresponding lines of your Schedule A.
2. Total them up.
3. Transfer that total to Line 12 of Form 1040.
4. Subtract this amount from your income to determine your final taxable income amount.
Make sure you keep thorough records, such as receipts and bank statements, to support your deductions. You'll also need to separate your business expenses from your personal expenses, since self-employed deductions are reported on Schedule C, not Schedule A.
No. The IRS requires you to pick one method for your entire return. You can’t itemize certain deductions while taking the standard deduction for others. If your total itemized deductions exceed your standard deduction, itemizing everything on Schedule A will generally save you more; if they don’t, the standard deduction is the simpler, more valuable choice.
Itemizing deductions can lower your personal tax liability, and posting business deductions decreases your taxes on business income. Both can be a huge help come tax filing season. If you have questions regarding personal vs. business itemized deductions, it’s best to ask a tax accountant or other tax professional.
Remember, the most important part of taking deductions is keeping your receipts. Doing so ensures that your deductions are as accurate as possible in the event of an audit.
Wading through receipts can be a headache, though. Fortunately, accounting software like QuickBooks Solopreneur allows you to manage files, taxes, and more all in one place.




Call Sales: 1-800-285-4854